Effective Tax Rate
Effective Tax Rate vs. Marginal Rate: Why Your Tax Bracket Isn’t Your Tax Bill
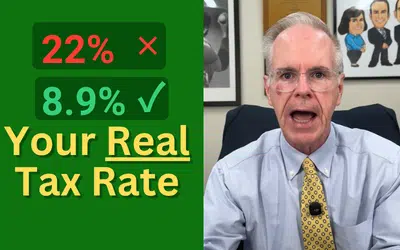
Tom explains the common confusion between marginal tax rates and the effective tax rate. Being in a 22% or 32% bracket only applies to the next dollar of taxable income (or the “last” dollar of income), not all income.
We discuss the progressive federal tax system, using 2026 married filing jointly brackets. Tom also offers a quick method to estimate your effective tax rate by dividing “total tax” by income on a tax return.
Using two $160,000 income examples, he shows how deductions change taxable income and taxes:
- a couple both 65+ has $113,100 taxable income, owes $14,306, and has an 8.9% effective rate.
- a younger couple has $127,800 taxable income, owes $17,540, and has an 11% effective rate.
Tom advises using marginal rates for decisions like Roth conversions and using the effective tax rate to describe total taxes paid.
Effective Tax Rate Links
Catch all our Mullooly Asset videos here
Subscribe to the Mullooly Asset YouTube Channel
Watch this episode (“Effective Tax Rate”) on our YouTube Channel
Effective Tax Rate Transcript
There’s a pretty common mix-up between the effective tax rate and marginal tax rates.
People hear you’re in the 22% tax bracket, and they treat that as the full rate that they’re going to pay this year in taxes.
That’s going to be the rate on the entire amount!
And that’s just simply not accurate.
What we like to stress to people is that when you hear “you’re in the 22% bracket,” you’re going to pay 22% on the next dollar of taxable income that you bring in.
If you’re in the 32% tax bracket, you are going to pay that rate on the next dollar that you earn.
So that is called the marginal tax rate.
But when you figure out what you owe in taxes, what you pay, this is called the effective tax rate.
And a little shortcut that I used to give people all the time was flip to the second page on your tax return, take a look at that number that says, “This is your total tax.”
Take that number, divide it into the income on page one of your tax return.
You’re going to find out that the actual percentage of your income that you pay in taxes is less than you think — for a lot of people.
We’re kind of surprised that people just don’t seem to understand the difference between the effective tax rate and the marginal tax rate.
If you’re new here, my name is Tom Mullooly. I own a financial planning firm in Wall Township, New Jersey, and I work alongside my three sons, who are CFPs just like me.
Okay, so a term that you’ve probably heard somewhere before, the federal tax system is a progressive tax system.
Remember that term progressive.
For a married couple filing jointly in 2026, the first $24,800 of taxable income gets taxed at 10%.
The next block, which is much larger than the first block, the next block is $76,000 of taxable income.
That gets taxed at 12%.
It’s only the income above those two combined, that’s $100,800 in 2026, of taxable income, those are the dollars above that line that get taxed at the next bracket, which is 22%.
So 22%…..in this instance….. is the rate on the top layer of income, not on the whole pile.
There’s a huge difference here.
Let’s take an example of a married couple, both of them are 65 years of age or older.
So for our example, they’ve got $160,000 worth of income.
Before we even begin to talk about brackets, a few things come off the numbers.
The first is their standard deduction for $32,200 in 2026.
Because they’re age 65, and they’re both age 65, they can knock off another $1,650 in 2026.
Just because they’re 65 and older.
And you heard about “no tax on Social Security!”
The way that they did this was they added an additional senior deduction of $6,000 per person.
That last one starts to phase out at $150,000.
And so in this example, it’s not the full $12,000, it’s $11,400 in this number.
It’s also worth noting that this senior deduction for $6,000 per person is temporary.
It’s only for tax years ’25, ’26, ’27, ’28.
When you do the math, you’re going to see that their taxable income is $113,100.
Remember, they started with $160,000.
They’re going to be taxed on $113,100.
This is just– This puts them just into the 22% bracket by about $12,300.
The federal tax on this situation adds up to $14,306.
The last dollars were taxed at 22%.
The tax bill for this married couple over age 65, $14,306.
That works out to an effective tax rate of 8.9%.
On that, say they are thinking about a Roth conversion?
Or they’re thinking about taking money out of a pre-tax retirement account.
Use the marginal rate for the decision about the next dollars that come into the equation, like a Roth conversion.
Use the effective rate to describe what is actually been paid in taxes.
Common mistake, quoting the bracket as the bill, what’s owed, really overstates the tax.
And in this example, it overstates the tax by more than double.
Let’s look at another example.
What if you have a married couple that has the same kind of income, $160,000, but they’re not 65 years of age or older, they’re younger.
So under 65, the only deduction that they’re going to get in this example is the standard deduction.
And in 2026, that’s $32,200.
So that 3,300 that they got, each of them were over 65 in the previous example, that goes away.
The senior deduction, that goes away.
So their income is $127,800.
We took the 160, we took off the standard deduction, we’re left with $127,800.
They are in the 22% tax bracket, just like the folks in the first example.
But these people are in the 22% tax bracket by $27,000.
$17,540 is the tax that they’re going to owe.
If you divide that into the $160,000 worth of income that they have, their effective tax rate is 11%.
Marginal tax rate? Still 22%.
Effective tax rate? Just 11%.
We get asked….. a lot…… whether folks should contribute to their retirement account as a Roth contribution or a pre-tax 401(k) contribution.
And for more on that topic, watch this video next…….